A practical guide to refinance pathways and scenario preparation
FINSTREET Easy Refi provides three refinance assessment pathways for eligible borrowers. The appropriate route depends on repayment conduct, the proposed financial benefit, documentation, borrowing requirements and product policy. This guide explains what to check and how to prepare a useful scenario for our Credit team.
A client can have a consistent mortgage repayment history and still face a refinance hurdle. The issue might be income evidence, standard servicing, the existing lender or the property being offered as security. Identifying that hurdle early helps you ask the right questions before preparing an application.
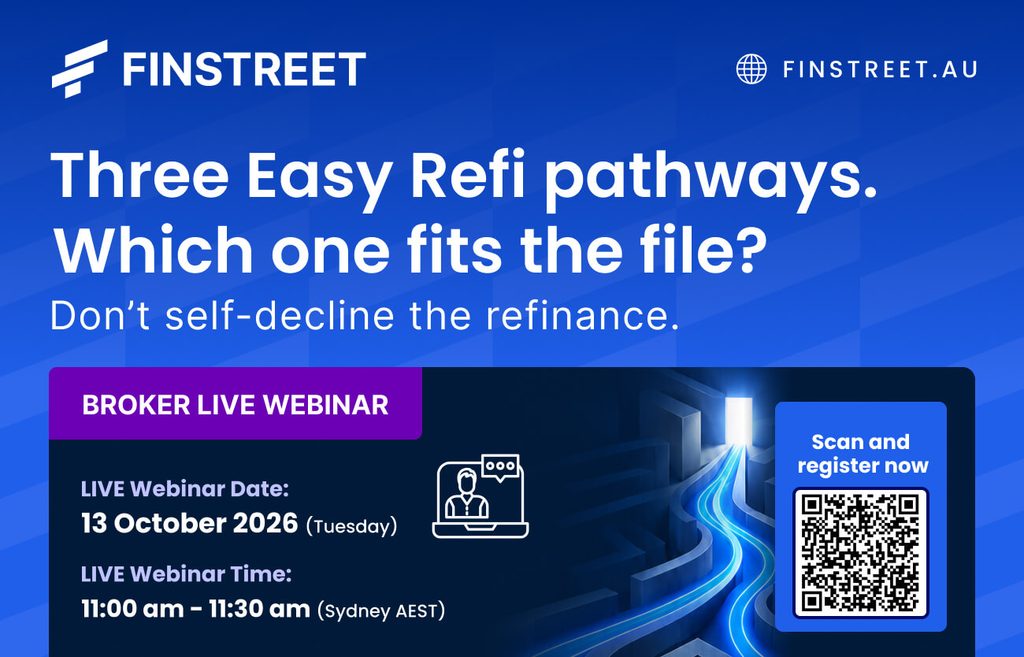
Join FINSTREET WEBINAR for a practical broker session on how to recognise the three Easy Refi pathways and prepare a cleaner scenario for early credit review.
Broker Webinar: Three pathways for refinance deals outside the standard box
Date: Tue, Oct 13, 2026
Time: 11:00 AM – 11:45 AM AEDT
WHAT BROKERS WILL LEARN
- Identify the repayment conduct, income evidence, servicing and current lender information that changes the answer
- Recognise where selected non-bank, eligible private lender, high-density and boarding house scenarios may be considered
- Package a useful headline scenario for FINSTREET Credit without over-preparing the file
- We’ll walk through the client’s circumstances, the challenges in the file and the key considerations that help identify a suitable Easy Refi pathway.
You will leave with a practical scenario selector and a clear list of the information our Credit Team needs for an early view.
Register here:
Do not self-decline the refinance. Bring the scenario.
What is Easy Refi
Easy Refi is FINSTREET’s range of refinance pathways for eligible existing borrowers. Depending on the selected pathway, the assessment may use a different documentation or servicing approach from a standard refinance. The client’s circumstances, loan conduct, security and proposed loan must still meet the applicable criteria.
How Easy Refi relates to Low Doc and Alt Doc
Low Doc and Alt Doc describe approaches to income verification. Easy Refi describes a refinance offering with its own eligibility and assessment requirements. These terms should not be used interchangeably.
Within the three pathways below, Clear Benefit and Alt Doc Dollar for Dollar do not require income documentation under the relevant policy, while Streamline Like for Like requires income documents. Applications, supporting records and credit assessment still apply. A streamlined process does not mean no documents or automatic approval.
Three Easy Refi pathways at a glance
Use this comparison to identify a potential starting point. FINSTREET Credit confirms the applicable product and current policy for the individual file.
| Key consideration | Clear Benefit Easy Refi | Alt Doc Dollar for Dollar Refi | Streamline Like for Like Refi |
|---|---|---|---|
| Main scenario | Borrower showing a clear financial benefit | Self-employed borrower seeking a simple refinance | Clean conduct but unable to meet standard servicing |
| Income evidence | Not required under this pathway | Not required under this pathway | Required |
| Calculator | Easy Refinance Calculator required | Standard Alt Doc Calculator required | No servicing calculator under the selected pathway |
| Indicative limits | Up to 80% LVR; $50,000-$3.5m | Up to 80% LVR; up to $5m | Up to 80% LVR; up to $2.5m |
| Additional funds | Up to 3% of property value, capped at $50,000 | Up to $10,000 for refinance costs | No cash out under the selected no-servicing pathway |
Limits are subject to the selected product, security, valuation and credit assessment. Debt consolidation is not available across these three pathways.
What to check for each pathway
Clear Benefit Easy Refi
Start by checking the proposed financial benefit. The new rate must be lower, and the new principal and interest repayment must be lower than both the existing contractual and actual repayments.
The repayment history requirement is at least 12 months for PAYG borrowers and 24 months for self-employed borrowers, with no repayment more than 15 days late. The existing loan generally needs to appear on comprehensive credit reporting, subject to limited policy exceptions. Confirm borrower structure, credit score and security eligibility before progressing.
Alt Doc Dollar for Dollar Refi
This pathway is for eligible self-employed borrowers seeking a dollar-for-dollar refinance, with up to $10,000 additional borrowing for refinance costs. The new rate and monthly repayment must be lower, and the term should be similar to the existing facility.
Prepare the latest 12 months of mortgage statements and check for missed payments on any facility during the previous 24 months. Other debt statements may be needed where repayment history is not available on the credit report. A completed application and signed Easy Refinance declaration are also required. Confirm the current calculator and documentation requirements with Credit.
Streamline Like for Like Refi
This pathway may be relevant where a client cannot meet standard servicing but has 12 months of clean repayment and credit history. Income documents are required. Under the selected pathway, a servicing calculator is not required; credit assessment and other policy checks remain in place.
The proposed rate and monthly repayment must be lower. No cash out is available under the selected no-servicing pathway. Existing lender eligibility and the security must be checked against the specific product rather than assumed from repayment conduct alone.
Why a lower repayment needs a closer look
Review the current balance, interest rate, contractual repayment, actual repayment and remaining term together. A lower proposed monthly repayment does not, by itself, establish the overall benefit to the client.
Include discharge, establishment and valuation costs, and any applicable break costs, in the comparison. Extending the loan term can reduce the monthly payment while increasing interest paid over time. ASIC’s Moneysmart guidance recommends checking switching costs and loan length when considering a refinance.
Read Moneysmart guidance on switching home loans
Can non bank and private lender loans be refinanced
Selected Easy Refi products can consider loans with non-bank lenders and eligible private lenders. Acceptance depends on the chosen product and the existing facility. Identify the lender, loan type, repayment arrangements and credit reporting position in the initial scenario.
High-density securities and boarding houses may also warrant a discussion with FINSTREET Credit. Provide the property type, location and estimated value so the team can check security eligibility. These scenarios require individual policy confirmation; they are not accepted automatically across all three pathways.
A practical scenario to consider
Illustrative example: A self-employed client wants to refinance an existing non-bank mortgage. The client reports consistent repayments and is seeking a lower rate without additional borrowing, but traditional income documents are not readily available.
The Alt Doc Dollar for Dollar pathway may be worth exploring. Before presenting it as an option, check the latest 12 months of mortgage statements, repayment conduct across all facilities over 24 months, the proposed rate and repayment, remaining term, loan-to-value ratio and borrower eligibility. The example identifies a possible starting point; it does not establish approval or eligibility.
What to include in your Easy Refi scenario
Give your FINSTREET BDM a concise summary that covers these eight points. Flag uncertainties upfront so the Credit team can identify what needs clarification.
- Borrower profile and structure: Employment type and whether the application involves individuals, a company or a trust.
- Existing lender and balance: Name the lender and describe the current facility.
- Proposed loan and LVR: State the requested amount and estimated loan-to-value ratio.
- Security: Include property type, location and estimated value.
- Current loan terms: Provide the rate, contractual and actual repayments, and remaining term.
- Repayment conduct: Summarise the relevant 12-24 months, including any late or missed payments.
- Income evidence and the blocker: Explain what is available and why the standard pathway does not fit.
- Additional funds and credit issues: State any cash out, its purpose and known adverse credit items.
Frequently asked questions
Is Easy Refi only for self employed borrowers
No. The Alt Doc Dollar for Dollar pathway is for eligible self-employed borrowers, while other Easy Refi pathways can cover different borrower profiles. PAYG, company or trust eligibility depends on the selected product and structure.
Does Easy Refi require income documents
It depends on the pathway. Income documents are not required under the Clear Benefit and Alt Doc Dollar for Dollar policies described here. They are required for Streamline Like for Like. Other documents and credit assessment remain necessary.
Can a client refinance if standard servicing does not work
A selected Streamline Like for Like pathway may be considered where the client has the required clean conduct and meets the remaining criteria. Income evidence is still required, and the absence of a servicing calculator does not remove credit assessment.
Can refinance costs be included in the new loan
Some pathways permit limited additional funds. Alt Doc Dollar for Dollar allows up to $10,000 for refinance costs. Clear Benefit allows up to 3% of property value, capped at $50,000. No cash out applies under the selected Streamline no-servicing pathway. Product and LVR limits still apply.
Does clean mortgage conduct guarantee eligibility
No. Credit history on other facilities, the existing lender, security, borrower structure, documentation and the proposed financial benefit can all affect the assessment.
Where can brokers download the comparison tool
The Easy Refi Scenario Selector is a one-page PDF with a three-pathway comparison and an eight-point scenario checklist. Use the download button below to keep a copy for your next file review.
Prepare your next refinance conversation
A useful first step is to identify the blocker and gather the key facts. Our team can then help clarify the potential pathway and the information needed to progress the assessment.
Have a file ready to review?
For broader product information, access FINSTREET product guides
For broker use only. This article provides general product information and does not constitute an approval or offer of credit. Eligibility, current lending policy, borrower circumstances, valuation, credit assessment, fees, charges, terms and conditions apply. Confirm current product requirements with FINSTREET before proceeding.